
 Facebook
 X
 Pinterest
 Copy Link
Step 1 to Buying a Home: Check Your Credit Score
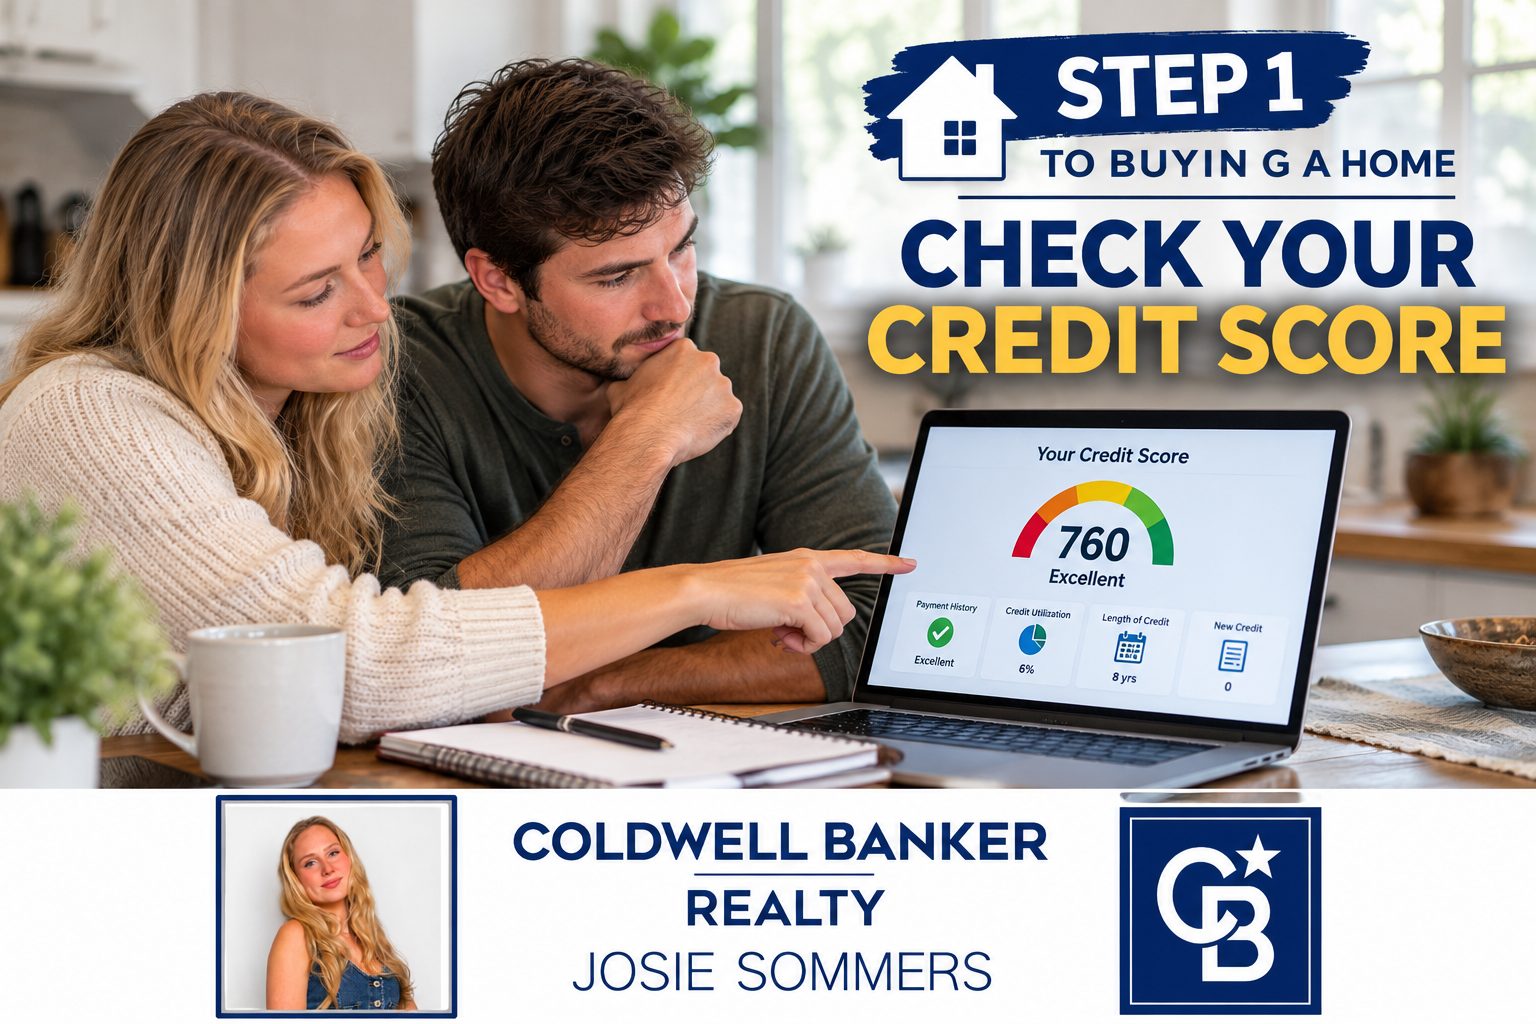
Before you look at a single house, find out where your credit stands. It’s the very first step, and it shapes everything that comes after it.
Hi, I’m Josie Sommers, a real estate agent with Coldwell Banker Realty. This is part one of my ten-part series walking you through the steps to buying a home. I’m starting with credit because if you’re buying your first home, this is the step that can surprise you the most, and it’s also the one you can start working on today.
Why Your Credit Score Comes First
When you apply for a mortgage, your lender looks at your credit to decide two big things: whether you qualify, and what interest rate you’ll get. A better credit score can mean a lower monthly payment for as long as you own the home.
Checking your score early gives you time. If it needs work, you can fix it before you start shopping, instead of finding out in the middle of the process.
My Own Credit Story
Not long ago, I didn’t have much credit to my name at all. I had a credit card, but that was about it. What really built my credit was buying my car and making that payment every single month. Paying it on time, month after month, showed lenders I was reliable.
That’s the big lesson I want you to take away: lenders want to see a track record. If you’ve never had a credit card, never had a loan, or never made a big purchase, there may not be enough history for a lender to judge you on yet.
One important caution, though. Don’t go take out a new car loan right before you buy a house just to build credit. A new monthly payment can lower how much home you qualify for. If you’re planning to buy soon, there are smarter, smaller ways to build your history (keep reading).
Your Credit Doesn’t Need to Be Perfect
This is one of the biggest myths I hear. People assume they need flawless credit and a huge savings account before they can even think about buying. That’s just not true.
- You don’t need perfect credit to buy a home. You need reliable credit, meaning a history of paying what you owe, on time.
- You may not need 20% down. For qualifying buyers, some loan programs allow as little as 3% down.
- A lender can tell you exactly where you stand and what you’d need to work on, often in one conversation.
How to Check Your Credit Score
Here’s the good news: checking your own credit does not hurt your score. It’s called a “soft” check, and you can do it as often as you like.
- Get your free credit reports at AnnualCreditReport.com. This is the official free site for reports from all three credit bureaus (Equifax, Experian, and TransUnion). Look for anything that seems wrong, like accounts you don’t recognize or late payments you know you made on time.
- Check your bank or credit card app. Many of them show your score for free.
- Keep in mind your mortgage lender may see a slightly different number. Lenders often use their own scoring models, so treat the app number as a helpful starting point, not the final word.
A Smart Credit Tip From a Loan Officer
I asked David Lozinski, a loan officer with First Equity Mortgage, what mistake he sees most often with people trying to build credit. His answer surprised me.
The biggest mistake is using credit cards too much. A lot of people run up big balances chasing airline miles and rewards, and it works against them.
Here’s what David recommends instead:
- Buy one small thing a month on your credit card.
- A few days later, log in and pay it off in full.
- Repeat every month. Your card shows it’s being used, but you never carry a balance.
Over time, often within about six months, your credit card company may start offering to raise your limit. Once you have a higher limit, you can use your card more like a normal credit card, while still keeping your balance low compared to your limit.
It sounds like a small trick, but small habits like this make a huge difference when you’re building credit.
Your Step 1 Checklist
- Pull your free credit reports and look for mistakes.
- Find your current credit score.
- If you have little or no credit history, start building it the smart way with one small purchase a month, paid off in full.
- Avoid opening big new loans or running up card balances before you buy.
- Talk to a lender early so you know exactly where you stand.
Ready to Take the First Step?
If you’re thinking about buying your first home and you’re not sure where your credit stands, I’d love to help you figure out your next step. There’s no pressure and no question too basic. Reach out anytime, and I can connect you with a trusted lender to get started.
Next week in the series: Step 2 of buying a home.
Josie Sommers, Coldwell Banker Realty
Helping first-time buyers across the Twin Cities.
Call or text: 952-454-8504
josie.sommers@cbrealty.com
